Mike Prenesti, The Mortgage Jedi
16 years helping Las Vegas homebuyers find the right loan. NMLS #1033445.
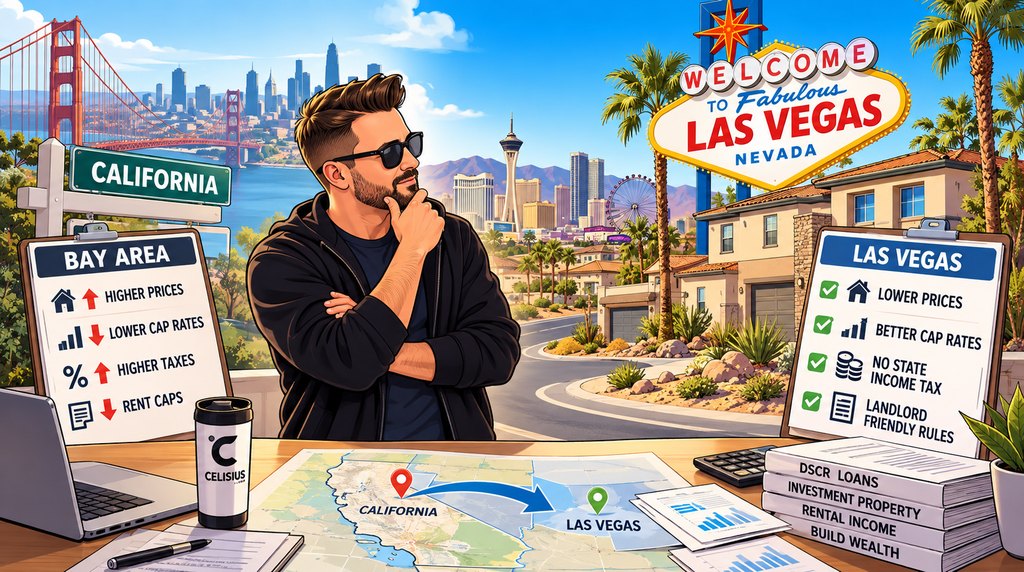
You are looking at a fourplex in Oakland. The cap rate is under 5%. Your loan rate is above 6.5%. Every dollar you borrow costs more than the property earns.
That math is why a lot of California investors have started looking at Las Vegas. Here is what is actually different, including the parts that do not favor Nevada.
Why the Bay Area Math Is Getting Hard
Cap rate is a property's annual net operating income divided by its price. A property that nets $50,000 a year and costs $1,000,000 has a 5% cap rate. It tells you what the property earns before any loan enters the picture.
Kidder Mathews reported that Bay Area multifamily averaged $313,445 per unit in the second quarter of 2026, down 10.4% from a year earlier, with an average cap rate of 5.7%. Some submarkets run well below that average.
Mortgage rates are sitting in the mid 6% range, and investment property loans typically price higher than owner-occupied loans. When the cap rate is lower than your loan rate, borrowing makes your return smaller, not bigger. The more you borrow, the worse it gets.
What Las Vegas Looks Like Next to It
Small multifamily in Las Vegas has generally traded at cap rates in the 5% to 6% range, with prices per unit that often run around half of what Bay Area buyers pay.
That does not mean every deal here works. A 5.5% cap rate against a 7% loan still loses money on the borrowed portion. What it means is there is more room to find properties that pencil, especially if you put more money down.
Check every property on its own numbers. An average tells you where to look, not what to buy.
Taxes and Landlord Rules: What Actually Changes
Nevada has no state income tax. California's top marginal rate is 13.3%.
Here is the catch. California taxes its residents on income from everywhere, including rental income from a Nevada property. The Nevada advantage shows up fully if you are a Nevada resident. If a move is part of your plan, talk to a CPA about timing before you buy or sell.
Two other differences are easier to count on.
Nevada caps annual property tax increases on investment property at 8%.
Nevada has no rent control. California's statewide rules cap annual increases at 5% plus CPI, up to a maximum of 10%, and some California cities have stricter local rules. In Nevada you can raise rent to market at lease renewal.
The Rent Growth Tradeoff
This is where I want to be straight with you. San Francisco rents have been climbing fast. Kidder Mathews reported asking rents up about 5.8% over the past year. Las Vegas rents have been roughly flat.
California's caps limit how much of that growth a landlord can actually collect. Nevada lets you collect all of it, but only if the market is growing. Do not buy in Las Vegas expecting rents to jump. Buy because the numbers work on today's rent.
How Financing Works When You Live in California
For most out-of-state investors, the first loan to look at is a DSCR loan.
DSCR stands for Debt Service Coverage Ratio. The loan qualifies based on whether the property's rent covers its own payment, including principal, interest, taxes, insurance, and HOA dues. No tax returns, no W-2s, no employment verification.
That matters for a California investor because your California tax returns and your other mortgages do not decide what you can buy in Nevada. Each property is judged on its own numbers. Expect a down payment around 20 to 25% and solid credit. Credit still counts even though income documentation does not.
Conventional investment loans are the other option. They use your personal income and debt-to-income ratio, and they can carry the best rate when you have strong documented income and a small number of financed properties. Conventional lending also tends to cap out around ten financed properties.
The right choice depends on the deal and on your situation. I run both side by side so you can see the real difference. If you want the full breakdown, here is how DSCR loans actually work.
Buying Out of State Without Flying In Every Week
Most of this can be done from California. A good title company can coordinate signing with a mobile notary or a local signing office near you, and your lender handles the file remotely.
What you do want on the ground in Las Vegas is a team. A lender who knows this market, an agent who knows the specific neighborhoods, and a property manager you trust before you close, not after.
Verify three things on every property. HOA rules, especially if you are thinking about short-term rentals. Current zoning and permitting for how you plan to use it. And a real insurance quote, not a placeholder.
If a wire is part of your closing, confirm the instructions by phone with a number you already know is real. Wire fraud targets out-of-state buyers.
Run the Numbers Before You Fall for the Property
Start with real rent, real taxes, real insurance, and HOA dues. Then add vacancy, management fees, and a maintenance reserve. Only then compare the result to your loan payment.
Most investors overestimate what a property earns. Conservative numbers protect you. For more on how I read this market, here is my broader take on investing in Las Vegas real estate.
Send Me the Property
If you are a California investor looking at Las Vegas, send me the address and the rent you expect. I will run the numbers, tell you honestly whether it works as a rental, and show you which loan structure fits best.
Get started here or book a call and send me the numbers on a property you are considering.
Frequently Asked Questions
Can a California resident get a mortgage for a rental property in Nevada?
Yes. Lenders care about the property and your qualifications, not where you live. Most California investors use either a DSCR loan or a conventional investment loan, and a down payment of 20 to 25% is typical.
What is a DSCR loan and why do investors use it?
A DSCR loan qualifies a rental property based on whether its rent covers its own payment, instead of using your personal income or tax returns. Investors use it because each property is judged on its own numbers, which makes it easier to keep adding properties. Self-employed investors and investors with heavy write-offs often prefer it.
Do I need to be a Nevada resident to buy investment property there?
No. You can buy as a non-resident. Many investors close in an LLC, and that is worth discussing with an attorney and a CPA before you sign anything.
How is Nevada's lack of state income tax relevant to a rental property investment?
It depends on where you live. California taxes its residents on all of their income, including rent from a Nevada property, so the benefit is limited while you are still a California resident. If you move to Nevada, the savings can be significant on both rental income and any gain when you sell. Run that question by a CPA before you buy.
What is the difference between cap rate and cash flow?
Cap rate measures what the property earns compared to its price, before any loan. Cash flow is what is left in your pocket after you pay the loan, reserves, and other costs. A property can have a decent cap rate and still produce thin or negative cash flow, depending on how much you borrow and what the loan costs.
Can I close on a Las Vegas property without flying in from California?
In most cases, yes. Your title company can set up signing with a mobile notary or a signing office near you, and your lender works the file remotely. Confirm wire instructions by phone before you send any money.
Have questions about your situation?
Let's talk it through. No pressure, no obligation.
Book a Free ConsultationRelated Posts
Asset Depletion Loans Explained: Qualifying on Savings and Retirement
If you have strong savings or retirement accounts but not a lot of documentable monthly income, asset depletion lets your savings and investments help you qualify without selling them.

Freddie Mac Asset Depletion Update: What Changed and Who It Helps
Freddie Mac reduced its asset-based income divisor from 240 to 180 months, which means roughly a third more qualifying income from the same savings. Here is what actually changed and when it takes effect.

Private Mortgage Loans: When Traditional Financing Isn't the Answer
Private and hard money lending exist for real reasons, speed, flexibility, unique situations. Here is when they actually make sense and when they don't.